What Happens If You Increase Your SIP by ₹500 Every Year?
Starting a Systematic Investment Plan (SIP) is one of the simplest ways to build a regular investment habit. But many investors ask an important question: What Happens If You Increase Your SIP by ₹500 Every Year? The answer is simple: a small yearly increase can significantly raise the amount you invest over the long term.
For example, if you start with a monthly SIP of ₹5,000 and increase it by ₹500 every year, your monthly contribution gradually becomes larger. As your income grows, your investment grows with it. This strategy is commonly known as a step-up SIP.
A step-up SIP can be useful for people who expect their income to increase over time. Instead of keeping the same SIP amount for many years, you increase your contribution gradually. This can help you invest more without making a sudden change to your monthly budget.
What Is a Step-Up SIP?
A step-up SIP is a regular SIP where you increase the investment amount at fixed intervals. Usually, investors increase the SIP once every year by a fixed amount or percentage.
For example:
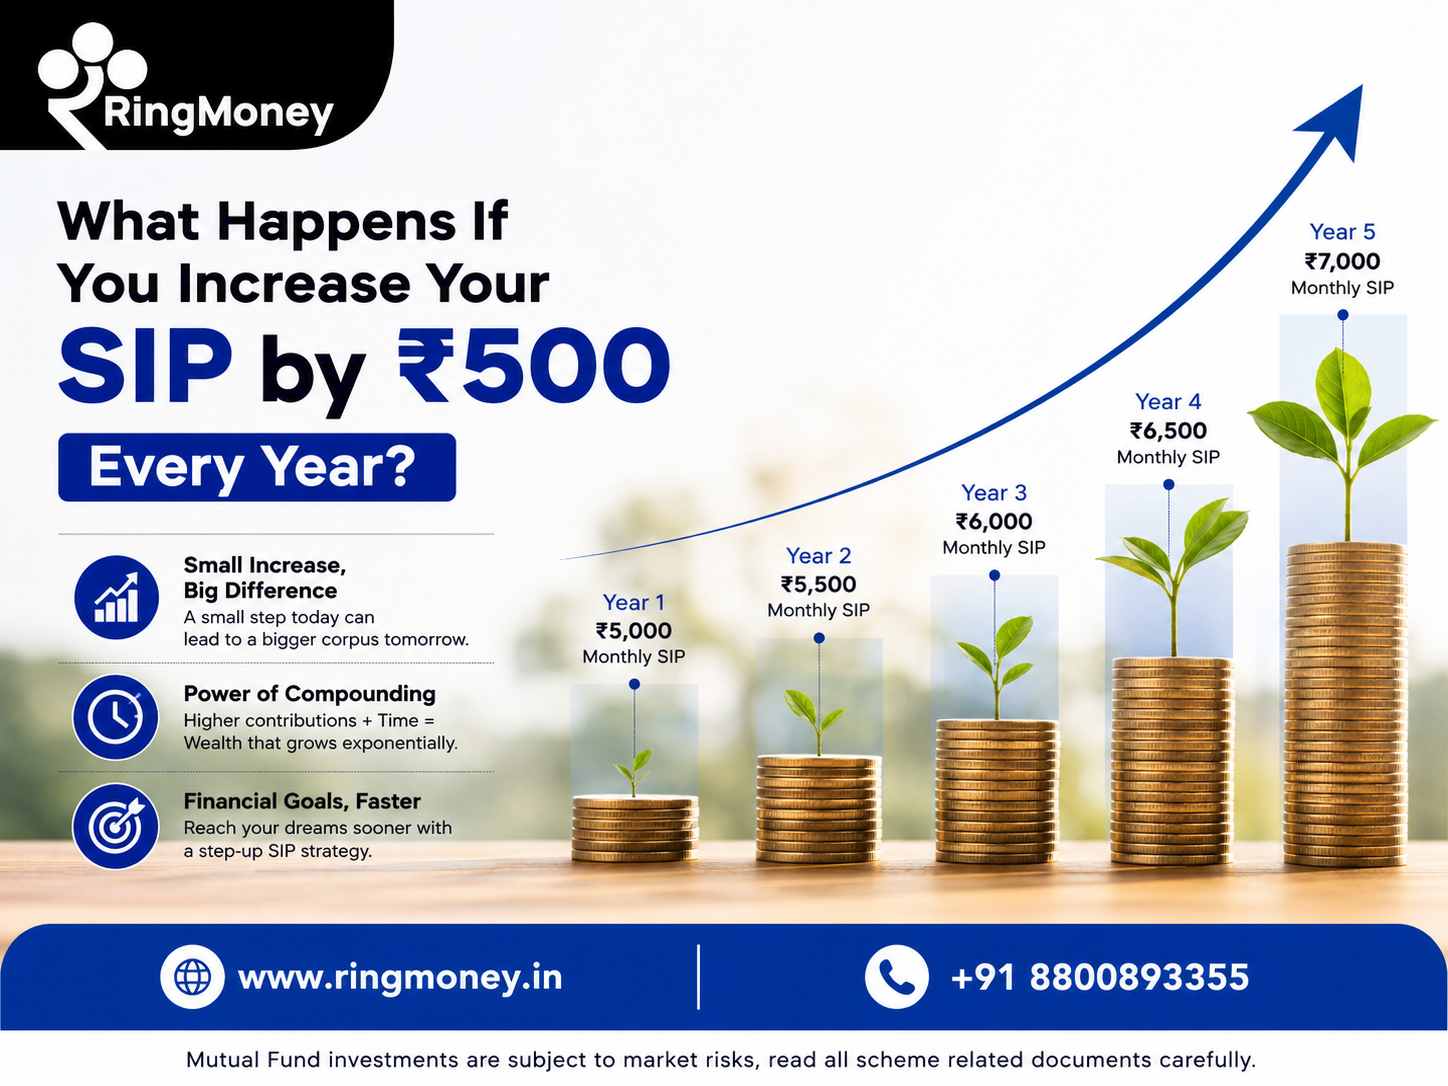
Year 1: ₹5,000 per month
Year 2: ₹5,500 per month
Year 3: ₹6,000 per month
Year 4: ₹6,500 per month
Year 5: ₹7,000 per month
Here, the investor increases the monthly SIP by ₹500 every year.
This method allows your investment to grow gradually. You do not need to start with a very high SIP amount. Instead, you can begin with an amount that fits your current income and increase it as your financial situation improves.
What Happens If You Increase Your SIP by ₹500 Every Year?
The biggest benefit is that your total investment increases with time. A ₹500 increase may look small, but repeating it every year can make a noticeable difference over a long period.
Suppose you start with a ₹5,000 monthly SIP. If you increase the SIP by ₹500 every year, your monthly investment will keep rising.
After several years, the difference between a fixed SIP and a step-up SIP can become substantial.
For illustration, assume a person starts with a ₹5,000 monthly SIP and increases it by ₹500 every year. If the investment earns an assumed annual return of 12%, the estimated corpus after 20 years can be significantly higher than that from keeping the SIP fixed at ₹5,000.
However, actual mutual fund returns are market-linked and can be higher or lower. The calculation should therefore be treated only as an illustration, not a guaranteed return.
Why Does a ₹500 Increase Matter?
Many people underestimate small increases because ₹500 does not seem like a large amount. However, investing is a long-term activity.
When you increase your SIP every year, three things happen:
- Your Monthly Investment Grows
Your SIP does not remain fixed. A ₹5,000 monthly SIP can become ₹5,500, then ₹6,000, and continue increasing.
- You Invest More Over Time
Every increase adds more money to your investment. Over several years, these additional contributions can become meaningful.
- Your Investment Can Get More Time to Grow
Money invested earlier gets more time to potentially generate returns. When you increase your SIP consistently, each additional investment gets an opportunity to participate in market growth.
This is one reason long-term investing and consistency are important.
Fixed SIP vs ₹500 Annual Step-Up SIP
A fixed SIP keeps your monthly contribution unchanged. For example, you may invest ₹5,000 every month for 20 years.
With a step-up SIP, you increase your contribution every year.
Investment Method Monthly Contribution
Fixed SIP ₹5,000 every year
Step-Up SIP ₹5,000 initially
After Year 1 ₹5,500
After Year 2 ₹6,000
After Year 3 ₹6,500
After Year 4 ₹7,000
The step-up approach requires you to invest more as the years pass. Therefore, you should choose an increase that you can comfortably maintain.
Benefits of Increasing Your SIP by ₹500 Every Year
Helps Build Investment Discipline
A regular yearly increase can make investing a habit. Instead of deciding every year whether you should invest more, you already have a planned increase.
Matches Growing Income
Many people receive salary increments, bonuses, or business income growth over time. Increasing your SIP can help you allocate a small part of that additional income towards investments.
Supports Long-Term Goals
Whether your goal is retirement, children's education, buying a home, or building wealth, investing more over time can help you work towards larger financial requirements.
Reduces the Impact of Inflation
Inflation gradually increases the cost of goods and services. A fixed SIP may not be enough to match your future financial requirements. Increasing your contribution can help your investment plan keep pace with changing needs.
Builds a Larger Investment Corpus
A higher contribution means more money gets invested. If your mutual fund investments perform well over the long term, the additional investment can potentially contribute to a larger corpus.
How Does Compounding Help?
Compounding is an important concept in long-term investing. When your investment earns returns, those returns can remain invested and potentially generate further returns.
For example, if your investment grows over several years, you are not only investing your original contributions but also allowing previous gains to remain invested.
A step-up SIP adds another advantage: your contribution increases over time. This means more money can participate in the investment journey.
However, compounding does not guarantee profits. Mutual fund investments are subject to market risks, and returns can fluctuate.
Example of a ₹500 Step-Up SIP
Consider an investor who starts with a monthly SIP of ₹5,000 and increases it by ₹500 every year.
The contribution may look like this:
Year 1: ₹5,000 per month
Year 2: ₹5,500 per month
Year 3: ₹6,000 per month
Year 4: ₹6,500 per month
Year 5: ₹7,000 per month
Year 6: ₹7,500 per month
Year 7: ₹8,000 per month
Year 8: ₹8,500 per month
Year 9: ₹9,000 per month
Year 10: ₹9,500 per month
By the tenth year, the monthly SIP has almost doubled compared with the starting amount.
This example shows why a small annual increase can become significant over time.
Is Increasing SIP by ₹500 Every Year Suitable for Everyone?
Not necessarily.
Your SIP should match your income, expenses, emergency savings, debt obligations, and financial goals.
Before increasing your SIP, consider:
Your monthly income
Essential expenses
Existing loans or EMIs
Emergency fund
Insurance requirements
Short-term financial commitments
Long-term investment goals
If your financial situation is unstable, it may be better to focus on building financial stability before increasing investments.
visit us: https://ringmoney.in/increase-sip-by-500-every-year/
When Should You Increase Your SIP?
You can consider increasing your SIP when your income rises or your monthly expenses become more manageable.
For salaried individuals, an annual salary increase can be a suitable time to review SIP contributions.
For self-employed people, the timing may depend on business income and cash flow.
The important point is to avoid increasing your SIP beyond what you can comfortably maintain.
₹500 or a Percentage Increase: Which Is Better?
There are two common ways to step up a SIP.
Fixed Amount Increase
You can increase your SIP by a fixed amount every year.
For example:
₹5,000 → ₹5,500 → ₹6,000 → ₹6,500
This method is easy to understand and plan.
Percentage Increase
You can increase your SIP by a fixed percentage every year.
For example, with a 10% annual increase:
₹5,000 → ₹5,500 → ₹6,050 → ₹6,655
A percentage-based increase grows faster as the SIP amount becomes larger.
The right method depends on your income growth and financial goals.
Common Mistakes to Avoid
Increasing SIP Without Checking Your Budget
Do not increase your SIP simply because others are doing it. Make sure the new amount fits your budget.
Stopping Investments During Market Corrections
Market movements are normal in mutual fund investing. Investors should avoid making emotional decisions based only on short-term market declines.
Ignoring Financial Goals
Your SIP should have a purpose. Understand how much you need and when you need it before deciding the investment amount.
Choosing a Fund Only Because of Past Returns
Past performance does not guarantee future results. Investors should consider risk, investment objective, fund strategy, and their own financial situation.
How Ring money Can Help
Planning a SIP is easier when you understand your investment objectives and financial capacity. Ring money provides information and guidance related to SIPs, mutual funds, and investment planning.
Investors can use such information to understand different investment strategies and make decisions based on their own financial goals and risk tolerance.
The goal should not simply be to invest more. The goal should be to create a sustainable investment plan that you can continue for the long term.
Final Thoughts
So, What Happens If You Increase Your SIP by ₹500 Every Year? Your monthly contribution gradually increases, your total investment becomes higher, and you get an opportunity to build a larger corpus over the long term.
A ₹500 increase may seem small today, but consistent yearly increases can make a meaningful difference over many years. A step-up SIP can also help align your investments with increasing income and changing financial goals.
However, returns from mutual funds are not guaranteed. Always consider your financial situation, investment horizon, and risk tolerance before making investment decisions.
The most important thing is consistency. Start with an amount you can comfortably invest and increase it gradually as your financial capacity improves.
FAQs
1. What happens if you increase your SIP by ₹500 every year?
Increasing your SIP by ₹500 every year increases your total investment gradually. Over a long period, this can potentially help you build a larger investment corpus compared with keeping the SIP amount unchanged.
- Is a ₹500 annual SIP increase enough?
There is no fixed amount that works for everyone. A ₹500 increase can be a good starting point if it fits your income and budget. You can choose a higher or lower increase based on your financial situation.
- What is a step-up SIP?
A step-up SIP is an investment plan where you increase your regular SIP contribution at predetermined intervals, usually every year. The increase can be a fixed amount or a percentage.
- Can I increase my SIP every year?
Yes, investors can increase their SIP contributions based on their financial capacity and the features offered by their investment platform or mutual fund provider.
- Does increasing SIP guarantee higher returns?
No. Increasing your SIP means investing more money, but it does not guarantee higher returns. Mutual fund returns depend on market performance and the selected investment.
- Should I increase my SIP after getting a salary hike?
If your financial situation allows it, increasing your SIP after a salary hike can be one way to allocate part of your additional income towards long-term investments.
- Is step-up SIP better than a fixed SIP?
A step-up SIP can be useful for investors whose income is expected to grow. However, a fixed SIP may be more suitable for someone who wants a stable monthly investment. The better option depends on your financial goals and capacity.
- Can a step-up SIP help with long-term goals?
Yes, gradually increasing your investment can help you allocate more money towards long-term goals. However, you should review your goals and investment strategy regularly.
- Is ₹500 too small for a SIP increase?
No. A small increase can still be useful when repeated consistently over many years. The important factor is choosing an amount that you can maintain comfortably.
- What should I consider before increasing my SIP?
Consider your income, expenses, emergency fund, debt, financial goals, investment horizon, and risk tolerance before increasing your SIP contribution.